Set your priorities
List your budget, bedrooms, preferred views and must-have amenities. Think about stairs, parking, pets, work-from-home needs and how often you’ll be in Cabo.

Baja International Realty · Buyer’s guide
Whether you are starting your research or preparing to make an offer, explore ownership, costs, property checks and rental considerations—then follow the purchase process through closing.
01 · Find your fit
A full-time home, a holiday retreat and a rental property can lead to very different shortlists. Decide what matters most, then compare the neighborhood as carefully as the home.
List your budget, bedrooms, preferred views and must-have amenities. Think about stairs, parking, pets, work-from-home needs and how often you’ll be in Cabo.
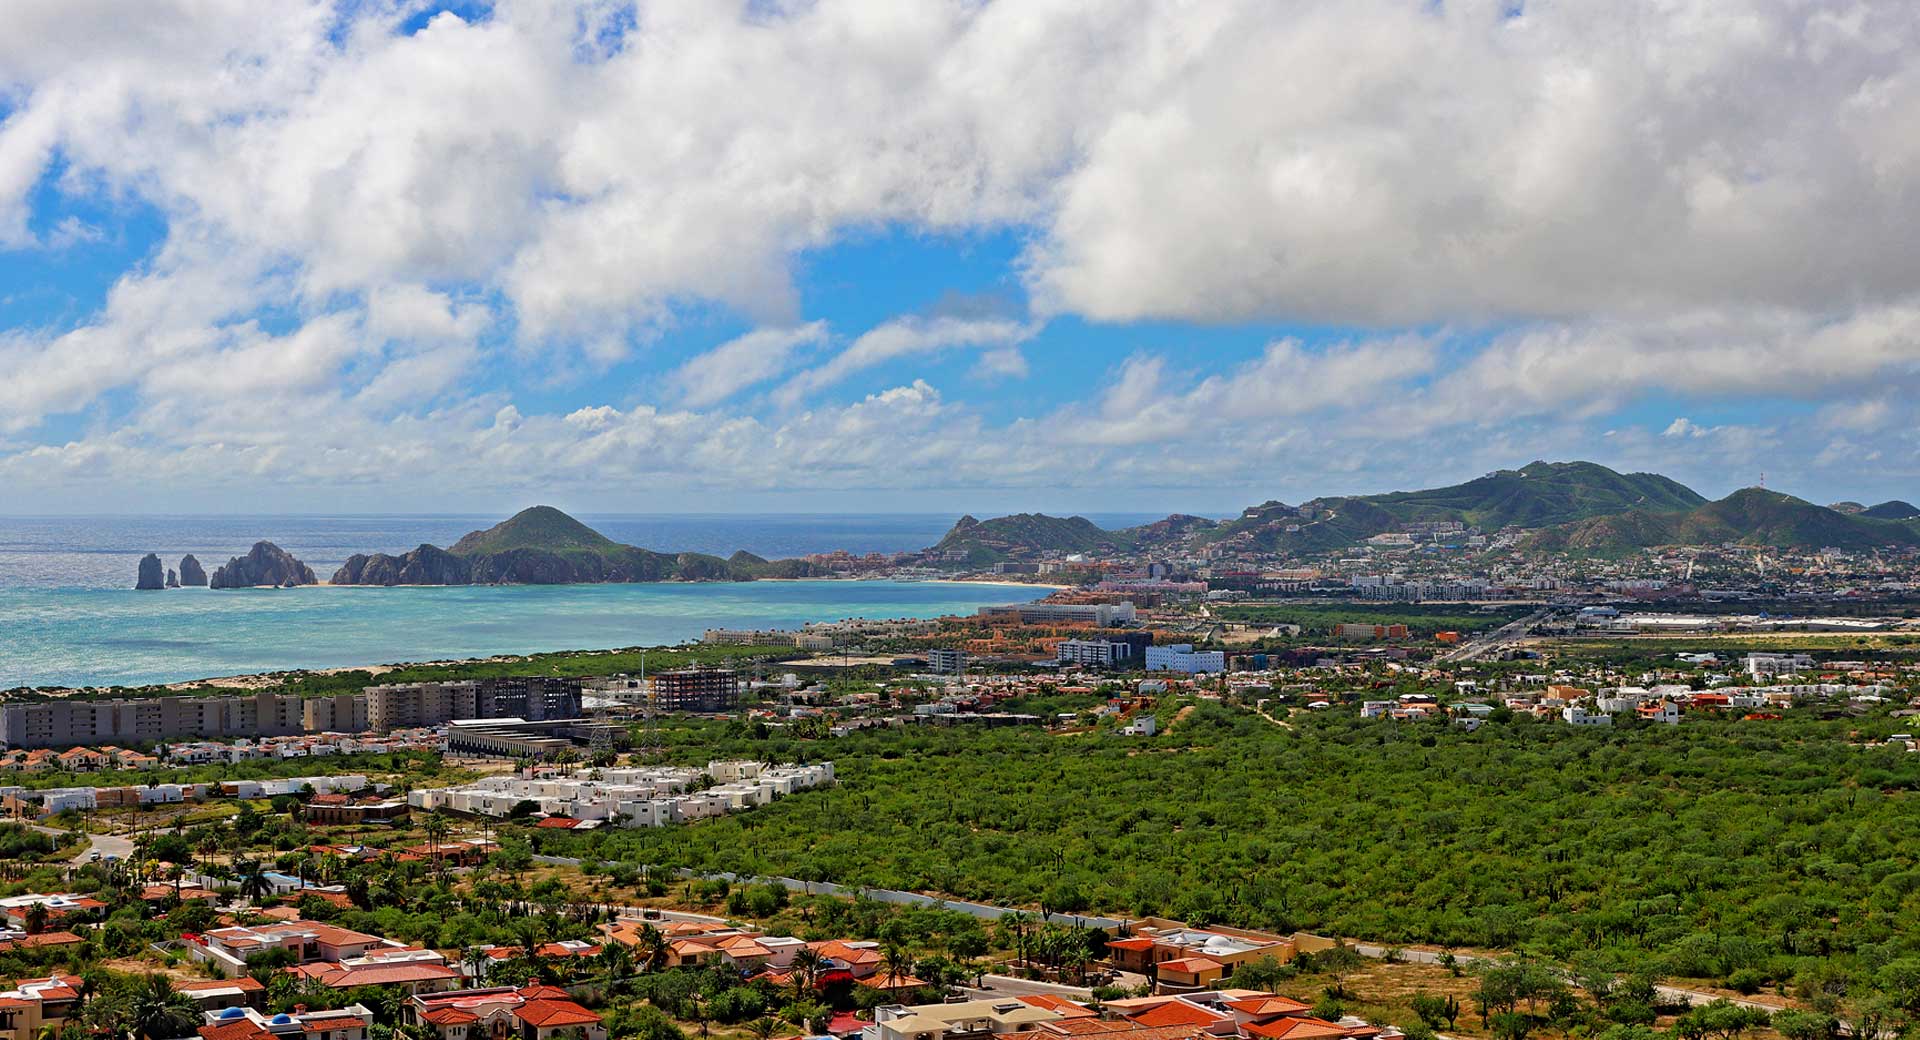
Compare Cabo San Lucas, San José del Cabo and the corridors. Visit the route to the beach, shops and everyday services. Check actual access and driving times during your viewing trip.
Start with ZONE, then work down through AREA, COMMUNITY and SUBDIVISION. Already know the development? You can search its subdivision directly. On our main BIR site, save favorites and compare your shortlist without signing up. Favorites stay in the same browser unless its data is cleared.
02 · Understand ownership
Yes. Americans and Canadians have been buying homes in Cabo for decades. For residential property in Mexico’s restricted zone, foreign buyers generally acquire beneficial rights through a bank trust called a fideicomiso. The zone extends 50 kilometers from the coast and 100 kilometers from international borders.
The Mexican bank acts as trustee, while the buyer is the beneficiary. The structure provides rights to use and enjoy the property under the trust. Federal law permits a term of up to 50 years, with an extension available on request.
Today’s renewal process: The 1993 Foreign Investment Law established the longer, 50-year term. The renewal application goes through the trustee bank to the Ministry of Foreign Affairs. Article 12 of the regulations provides that the extension shall be granted when the applicable trust conditions remain in place and have been fulfilled. It specifies applying within the 90 business days before the contract expires. Coordinate the documents and timing with your trustee bank.
Foreign Investment Regulations, Article 12: trust renewal.
Source: Mexico’s Foreign Investment Law, Articles 2 and 11–13.
Yes. A foreign legal entity, such as an LLC, can be named as the trust beneficiary, subject to the bank’s documentation and permit requirements. The bank still holds title as trustee; the LLC holds the beneficial rights.
Whether this is useful for your estate plan, liability arrangements or taxes is a question for your advisors back home.
Consider the tax consequences before using an LLC. Mexico’s qualifying home-sale ISR exemption is for individuals. If the LLC is treated as the seller and taxpayer, it cannot claim that individual exemption. Holding the trust rights through an LLC can therefore eliminate an exemption you might otherwise qualify for personally. An LLC’s pass-through treatment in your home country does not automatically carry over to Mexico.
Have your advisors confirm the Mexican treatment and any applicable treaty provisions before choosing the beneficiary. This is a potential exemption from tax, not a residential tax credit.
Foreign entities as beneficiaries: Article 11 · Income Tax Law, Articles 4-A and 93(XIX)(a)
Mexican families also use trusts for inheritance planning. Naming successor beneficiaries is a useful part of the structure, not simply a requirement for a foreign buyer. Ask how your bank updates beneficiary designations and which documents your successors will need.
BBVA: estate-planning trusts used in Mexico.
You can name successor beneficiaries in the trust to receive your rights after your death. Properly arranged, this can avoid a Mexican probate proceeding for the property held in the trust and make the transition easier for your family.
Keep the designations current and coordinate them with your estate plan. The bank will still require documents and formalities; fees and any applicable taxes must be checked.
If you are buying a couple of properties specifically to operate as rentals, compare the full cost of a fideicomiso with a Mexican company, where the intended use qualifies for corporate ownership. Savings on trust fees need to be weighed against incorporation, accounting, tax filings and ongoing company administration.
Your rights are transferable through the required formalities. A sale to another foreign buyer can use an assignment of trust rights; a sale to a Mexican buyer can involve the bank conveying title and ending the trust. Review the contract, remaining term and transaction costs with the bank and notario.
Trust sources: INVEX: successor beneficiaries and succession · Banorte: residential trusts and resale. The administration comparison is a practical consideration, not a guarantee of lower total costs.
An eligible individual selling their qualifying home held through a bank trust (fideicomiso) may qualify for Mexico’s home-sale income-tax (ISR) exemption. In property sales, ISR on the gain is commonly referred to as “capital-gains tax”; the legal exemption is part of Mexico’s income-tax law. This is an exemption, rather than a tax credit, and it is not automatically granted because the property is in a trust. A corporation selling its property cannot claim this individual home-sale exemption.
Two owners can each qualify. When two individuals own the home—such as a husband and wife—each may claim the home-sale exemption against their own share of the sale proceeds, provided each meets the requirements. For two qualifying equal owners, that can mean up to 1.4 million UDIS of combined exempt proceeds, rather than 700,000 UDIS for one owner. The exemption is assessed separately for each person; having two names on the title does not automatically double it.
Ask the notario to confirm the exemption for your circumstances and trust arrangement before agreeing to a sale. A vacation or investment home does not qualify merely because it is residential property. Any tax due in your home country is a separate question.
Tax sources: Income Tax Law, Article 93(XIX)(a) · SAT: proportional treatment of co-owners · SAT: proof that a property is your home · SAT: current tax rules, including foreign-seller residency (Rule 3.11.3).
For someone buying two or more properties to run as a rental business, this is a practical comparison of ownership eligibility, total costs and taxes. Start with how the properties will actually be used.
A Mexican corporation with foreign shareholders can acquire direct title in the restricted zone for qualifying nonresidential purposes, subject to the applicable requirements and notice to Mexico’s Ministry of Foreign Affairs (SRE). It is not a way to bypass the bank-trust requirement for a personal residence.
The distinction depends on use. The regulations treat property used exclusively as housing for the owner or third parties as residential. Certain commercial, tourism and development activities fall within the nonresidential rules. Simply calling a home an “investment property,” renting it out or buying several homes does not by itself establish eligibility.
Official guidance: SRE: acquisitions by Mexican companies with foreign shareholders · Foreign Investment Regulations, Article 5.
For a foreign buyer’s house or condo used as a residence in Los Cabos, a fideicomiso is generally the appropriate route. A foreign-owned Mexican corporation cannot take direct title under the nonresidential exception merely to save trust fees.
First confirm that the intended use qualifies. Then compare the full costs: incorporation, accounting, tax filings and ongoing administration may outweigh any savings on bank-trust fees. A corporation is not automatically the more economical choice.
A corporation may be worth considering for multiple qualifying properties, a development or an operating business. Evaluate the portfolio as a whole; no particular number of properties guarantees lower costs or changes the residential-use rules.
For a Mexican company taxed under the general corporate regime, a property sale normally enters the company’s tax calculations rather than the individual seller’s ISR payment handled by the notario at closing. This can change cash flow and lets the annual calculation account for the company’s permitted deductions and applicable losses.
It does not mean all tax can wait until year-end. Companies generally make monthly provisional ISR payments and reconcile the final liability in their annual return, normally due by March 31 of the following year. A sale can affect those provisional payments. With an individually held trust, the seller’s tax status and transaction determine the closing payment and any later filing.
Also compare taxes when company profits are distributed to you. A corporation cannot claim the individual home-sale exemption, and a true rental property does not automatically qualify for that exemption under a personal trust either.
Income Tax Law: Articles 9, 14, 93 and 126 · SAT: monthly company tax payments
Corporate compliance reference: SAT: Income Tax Law, Article 76 (accounting and annual returns). Cost comparisons above are practical considerations; obtain estimates for your specific transaction.
The May 1989 regulations provided a route for a 30-year trust to continue through a new trust over the same property, subject to the required permits and conditions. Buyers often described this as “30 plus 30.” When a property sold to a different beneficiary, a new trust could begin a fresh term of up to 30 years. A sale alone did not automatically restart the term.
Historical reference: 1989 regulations, Articles 20–21, reproduced in a UNAM thesis (printed pp. 104–107; Spanish PDF). These historical rules differ from the 50-year framework used today.
Foreign ownership through a fideicomiso is an established process. Don Weis recalls Stewart approaching him in the late 1980s and offering him the exclusive rights to offer title insurance throughout Mexico. He remembers renewable trust arrangements and title insurance as important steps in building foreign buyers’ confidence. This is Don’s recollection of his involvement in the market, separate from the legal requirements governing a purchase today.
Stewart’s company history records a further milestone: in January 2002 it opened Stewart Title Guaranty de México, the first Mexican title insurance underwriter licensed by the CNSF. For a purchase today, ask about the availability, coverage and exclusions of a policy for the particular property. Title insurance does not replace investigation of the title or the closing process.
03 · From your goals to your keys
Start with a clear purpose. Then choose people whose experience helps you understand the property, recognize the tradeoffs and make a decision that fits your goals. The sequence and timing will depend on your purchase.
Write down what you want this purchase to accomplish: a full-time home, a vacation retreat, rental income, a future retirement home or a combination. Define your total budget, ongoing-cost comfort level, timeline, expected use and how long you plan to hold the property.
Separate essentials from preferences, and discuss them with anyone buying with you. If financing is needed, investigate availability early. Bring this brief to your first agent meeting so the search starts with your goals.
A pleasant personality matters, but it is not enough. Choose an agent with relevant Los Cabos experience who asks thoughtful questions and explains neighborhoods, comparable properties, ownership costs and potential concerns clearly.
Ask about recent purchases like yours, client references, whom they represent and how they communicate. Does their knowledge give you confidence? If the answers remain vague or unconvincing, interview another agent before committing. Use the agent’s expertise to build a focused shortlist.
View the homes and their surroundings with your agent. Expect a balanced explanation of price, condition, community rules, recurring costs, location and suitability for your intended use. A capable agent raises concerns and brings in specialists when a question needs legal, tax or technical expertise.
Once you choose the property, your agent will prepare the offer for your review, including the price, currency, inclusions, deposits, conditions and dates. Read it carefully and ask questions if anything is unclear. Once you are comfortable with the offer, sign it and your agent will submit it to the seller. Then await the seller’s response and work toward acceptance; the seller may accept, counter or decline.
Once the offer is accepted, hire an experienced independent Mexican real-estate closing attorney with a strong local reputation. Your agent can refer you to one or two professionals; confirm their credentials, references, fees and whom they represent. The attorney will coordinate opening escrow for your first deposit, typically due within 5–10 days, as specified in the accepted offer.
Meet that deadline. If your agreement makes timely funding a condition of the purchase, missing it may make the offer null and void.
If you negotiated a building-inspection contingency, arrange the inspection promptly—typically within an agreed 7–10-day period. The deposit is held in escrow under the escrow agreement while the contingency is addressed. Your right to cancel and recover funds depends on meeting the contract’s conditions and notice deadlines. Once you approve the findings and formally release the contingency, the closing process continues.
For a foreign buyer, allow approximately 45–90 days from an accepted offer to closing as a planning range. Trust arrangements, title issues, financing and document readiness can extend that timeline.
Your closing attorney and agent work together to manage and resolve issues, coordinate the remaining work and keep you informed. When they need you to make a decision, they will present a clear explanation of the issue, your options and the implications of each, so you can make an informed decision with confidence.
Coordinate the trust, documents, itemized costs, payment arrangements and signing with the notario, bank and other specialists. Understand any unresolved issue and its consequences before deciding whether to proceed under your agreement.
Your attorney will coordinate the final review, signing and handover with the notario and your agent, then follow through on registration and delivery of the final deed or trust documents.
Confirm possession, keys, access devices, included items and any outstanding commitments. Arrange utilities, insurance and HOA or management contacts. Keep a written list of anything still pending, with a responsible person and a completion date.
Your independently retained attorney advises you and coordinates the work agreed in your engagement. Mexico’s notario público is a legally qualified public official who must act impartially, formalizes the deed, handles applicable taxes and oversees registration formalities. Your attorney works alongside the notario; hiring an attorney does not replace the notario’s role.
Further reading: NAR: questions to assess an agent’s experience (general interview guidance) · GOV.UK: choosing independent legal advice for an overseas purchase · Notariado Mexicano: the notario’s role. The recommendations and typical deposit and inspection periods above reflect our approach to a well-managed purchase; your signed agreements control. On closing coordination and timing: Cabo Closing Services.
04 · Plan beyond the price
Closing costs can be higher than buyers initially expect. A major component is Los Cabos’ 3% property acquisition tax (ISABI), calculated on the applicable taxable value under the municipal rules. Notarial services, registration, certificates and appraisal also contribute. For a new fideicomiso, the permit, bank setup and first annual fee add to the upfront cost.
Some closing charges are fixed or do not rise in direct proportion to the price. This can make closing costs a smaller percentage of a higher-priced purchase.
Request a written, itemized estimate for the specific property. Confirm the taxable value, any applicable reductions and the amounts included; a single percentage cannot capture every purchase.
Los Cabos municipal tax law, acquisition-tax provisions.
| Budget item | What to request or confirm |
|---|---|
| Purchase funds | Price, agreed currency, deposit schedule, exchange-rate arrangements and bank-transfer charges. |
| Closing costs | Acquisition tax, notarial fees and applicable VAT, registration, certificates, appraisal and other transaction expenses, itemized by the notario. |
| Bank trust, if needed | Setup or transfer costs, permit-related charges and the bank’s ongoing administration fee. |
| Financing, if used | Interest rate, currency, term, lender fees, insurance requirements and early-repayment conditions in the actual loan offer. |
| Ongoing ownership | Property tax, HOA dues and assessments, insurance, utilities, maintenance and any property-management fees. |
| Move-in and setup | Furniture not included, repairs, utility connections and an allowance for initial improvements. |
Closing-cost categories: Notariado Mexicano: property deeds and purchase expenses. Obtain current local figures for your transaction.
These new-trust estimates supplied by Loyalty Consulting on September 21, 2026 show how the total changes with the purchase price. All amounts are in US dollars. Open a price below to see the full breakdown; you can open several to compare.
Each line shows the base fee and the total including 16% IVA.
Total estimated closing costs: $19,534
Advance payment included in total closing costs: $6,014. This deposit covers miscellaneous fees due before closing. It is part of the total estimated closing costs above, not an additional charge.
Each line shows the base fee and the total including 16% IVA.
Total estimated closing costs: $39,339
Advance payment included in total closing costs: $7,134. This deposit covers miscellaneous fees due before closing. It is part of the total estimated closing costs above, not an additional charge.
Each line shows the base fee and the total including 16% IVA.
Total estimated closing costs: $73,169
Advance payment included in total closing costs: $9,310. This deposit covers miscellaneous fees due before closing. It is part of the total estimated closing costs above, not an additional charge.
Transcribed from Loyalty Consulting’s estimates, prepared by Lic. Jose Eduardo Garibay Perez. These are illustrative estimates, not fixed quotes, and do not authorize payment or engage a closing provider. Amounts can change, including with exchange rates; the provider states that final amounts are supplied after registration. Some receipts may be issued in the seller’s name while the property remains registered to the seller.
The acquisition-tax amounts in these samples equal 3.1% of the stated prices. They reproduce the preparer’s figures; ask for clarification of that calculation in your individual quote rather than treating it as the statutory rate. Check whether escrow, inspection, title insurance or financing charges apply and are included.
Your ownership budget
For this illustration, assume the municipal assessed value (valor catastral) equals US $500,000, or MXN $8,855,000 at 17.7100 pesos per US dollar, Banco de México’s latest available FIX rate, dated September 25, 2026. Your actual assessed value can differ from the purchase price.
Annual base rate: 0.115331% of assessed value
Without discount
US $577 / year
Approximately MXN $10,213
With a 20% early-payment discount
US $461 / year
Approximately MXN $8,170
Annual base rate: 0.22997% of assessed value
Without discount
US $1,150 / year
Approximately MXN $20,364
With a 20% early-payment discount
US $920 / year
Approximately MXN $16,291
Illustrative base predial only, rounded to whole dollars and pesos; excludes other charges or arrears. The 20% discount was available in January and February 2026 and is not a current September offer. Future discounts depend on municipal approval. Use the property’s actual assessed value, classification and tax bill for your budget; a vacation home or short-term rental may have a different classification.
Sources: Los Cabos tax law, Article 29; Banco de México FIX exchange rate; 2026 early-payment discounts.
The upfront purchase costs and your annual budget answer different questions. Many buyers find their local property tax lower than they are used to in the United States or Canada. Review the actual predial bill for the property, its municipal assessed value and classification, rather than applying a foreign tax rate to the purchase price.
Then add HOA dues, special assessments, insurance, annual trust fees, utilities and maintenance. A home with a pool, extensive landscaping or substantial air-conditioning use has a different budget from a smaller condo. Coastal exposure also affects maintenance. Request recent bills and an explanation of unusual expenses.
Property-tax reference: Los Cabos municipal tax law. Use the property’s current bill to build your budget.
Buying with rental income in mind
Begin with the property’s rules and the guests you hope to attract. Confirm that your intended rental use is permitted, including minimum stays, occupancy, guest registration and amenity restrictions. Read the actual condominium and management documents; a neighboring rental does not establish what you may do.
Beachfront visitors may pay a premium for immediate access to the water and the setting. You will usually pay more to buy that location too. A home directly behind a beachfront property can perform very differently. Compare actual rental histories and purchase costs, rather than assuming similar homes will earn similar income.
For fishing visitors, convenient access to the marina may matter most. Other guests want to walk to restaurants, bars and town activities without a car or taxis. Evaluate the route guests will actually take, not just a straight-line distance on a map. Identify the visitor you want to attract and compare properties serving that visitor.
When nearby rentals offer essentially the same experience, price becomes an easy way to choose between them. A distinctive outdoor space, thoughtful design, comfortable furnishings or amenities suited to your guests can help your property stand out at any price level. Photographs should accurately represent what visitors will find.
In BIR’s experience, repeat guests are an important part of a durable rental business. Direct repeat bookings can reduce platform charges, depending on booking terms and the management agreement. Establish who maintains guest relationships, how future reservations are handled and which fees still apply. Honor existing platform terms.
Ask how the manager handles arrivals, guest questions, cleanliness, maintenance and problems during a stay. Review the full fee schedule and reporting, not just a headline commission. Great management delivers or exceeds guests’ expectations and gives them a reason to return.
A vacation rental can leave room for your own visits, while a longer-term rental commits the property to a tenant for the agreed period. Before buying, confirm minimum stays, guest access and any required rental-management arrangements. A fideicomiso can accommodate permitted rental use; the property and community rules still need to fit your plans.
Request actual rental statements where available: nights available, nights booked, rates achieved and expenses. Separate owner stays from vacancy. A projected calendar is not a documented rental history.
Subtract management and booking fees, cleaning costs you absorb, utilities, maintenance, insurance, HOA charges, applicable taxes and other ownership expenses. Allow for replacements and periods without guests. Compare conservative and expected occupancy scenarios, especially if rental income is needed to support the purchase. Higher nightly rates do not guarantee better net results.
Rental strategy reflects Baja International Realty’s local experience, not a forecast of returns. Property permissions and operating requirements must be checked for the intended use.
05 · Look beneath the surface
Title and lien checks: Notariado Mexicano: protecting your property.
06 · Buying before completion
A model unit or rendering helps you picture the project. Your purchase agreement should identify the actual unit, specifications, included finishes, payment milestones and delivery terms.
For purchases from developers and other covered housing suppliers, Mexico’s NOM-247 sets requirements for marketing and contracts. PROFECO provides a public registry where you can check the supplier’s registered contract.
Closing essentials · The funds
Escrow is an arrangement in which a third party holds the buyer’s deposit or other purchase funds and releases them according to written instructions agreed for the transaction. In a Los Cabos purchase, it bridges the period between an accepted offer and closing: the buyer has a defined process for handling the money, and the seller can receive confirmation that the required funds have arrived. Escrow is available in Mexico, but it is not a legal requirement for every property sale.
At Baja International Realty, we offer buyers and sellers a choice of escrow companies located in the USA or Mexico.
Conde, Álvarez y Asociados: closing FAQs.
The parties agree on the provider and sign the escrow documents. The buyer funds the account on the timetable in the purchase agreement. The provider acknowledges receipt, holds the funds and makes authorized payments when the specified conditions and instructions have been satisfied. At closing, an itemized statement should explain the amounts paid to the seller and other recipients. The escrow provider administers the funds; your attorney and notario perform the legal work needed for the property transfer.
Have your attorney explain the deposit deadline, inspection or other contingencies, cancellation notices, release approvals and refund procedure. Ask what documents are required to release or return money, and how conflicting instructions are handled. A purchase-contract contingency and the escrow provider’s release procedure need to work together. Neither side should assume that simply requesting the money is enough to obtain it.
Ask who the contracting company is, where the money is held, which law governs the account, what licensing or insurance actually applies, and how fees, currency conversion and transfers are charged. Providers serving Mexican purchases use different legal structures; the word “escrow” alone does not establish identical safeguards. Purchase-funds escrow also has a different purpose from the residential fideicomiso used by many foreign owners to hold rights in coastal property.
TLA: escrow arrangements and provider checks. Your provider’s signed agreement defines its responsibilities and release requirements.
Closing essentials · Your legal advisor
A buyer’s closing attorney is a Mexican lawyer retained to advise the buyer and manage the legal work included in the engagement. The role combines legal review with coordination: identifying concerns, explaining choices and keeping the required documents and participants moving toward closing. Hiring a private attorney is distinct from using a notario. The attorney’s client relationship should be clear from the start.
Cabo Closing Services: attorneys and notarios.
The exact assignment should be agreed in advance, including ownership-structure work, powers of attorney, the cost estimate and follow-through after signing. Your attorney and agent should manage issues together and bring you clear explanations whenever your decision is needed.
Conde, Álvarez y Asociados: legal representation and closing coordination.
Look for relevant Mexican property experience, a verifiable professional license, clear fees and a named person responsible for updates. An experienced agent can suggest candidates, but the buyer chooses whom to retain. Ask who the firm represents, how potential conflicts are handled and whether specialist work or litigation would require a separate engagement. If language is a barrier, arrange reliable translation so important documents are understood.
GOV.UK: choosing independent legal advice for overseas purchases.
Closing essentials · The formal transfer
A Mexican notario público is a legal professional authorized by the state to give public authenticity and legal certainty to acts and documents. In a property sale, the role goes far beyond witnessing a signature. The notario must act impartially toward the parties, even when one side selects the office or pays the transaction’s notarial costs.
The office reviews the formal requirements for the transfer and prepares or authorizes the public instrument, commonly called the escritura. The notario handles the applicable tax calculations, collections or withholdings and filings within their legal responsibilities, and arranges registration of acts that require it. Your closing attorney coordinates with that office; the attorney does not replace the notario’s public function.
Colegio Nacional del Notariado Mexicano: the notario’s role and duties.
Title review includes checking the registered ownership and relevant liens or recorded restrictions. An existing mortgage, for example, requires proper attention to its release; paying a loan and removing the registered lien are different steps. Ask the team to explain how any identified issue will be addressed.
Notariado Mexicano: property records · Mortgage cancellation and recorded liens.
Request an itemized estimate: money collected through the notario’s office can include taxes, registry charges and other third-party expenses as well as the office’s own professional fees. For sellers, the tax review belongs at the start of sale preparation, before the property goes on the market. After signing, keep track of registration and delivery of the final documents rather than assuming every administrative step is finished that day.
Notariado Mexicano: understanding transaction costs.
07 · Common questions
For foreign buyers, approximately 45–90 days from an accepted offer to closing is a useful planning range, not a guaranteed completion date. The initial deposit is typically due within 5–10 days, and a negotiated building-inspection period may be 7–10 days. Your signed agreement sets the actual deadlines, when each period begins, whether days are calendar or business days, and the consequences of missing a deadline. Trust arrangements, title review, financing and document readiness affect the overall schedule. Presale delivery is a separate timeline.
Your agent helps you evaluate properties, understand tradeoffs and negotiate. Your independently retained closing attorney advises you, reviews the contract and coordinates the legal review and closing within the agreed engagement. The notario acts impartially, formalizes the transaction and handles required tax and registration procedures. An inspector evaluates physical condition, and the trustee bank handles the trust where needed.
A properly prepared power of attorney may allow a representative to act for you. Have the closing notario approve the required wording and formalities before arranging signatures abroad. Mexican consular guidance on powers of attorney.
Confirm possession and document delivery, set up utilities and insurance, introduce yourself to the HOA or property manager, and record due dates for taxes, fees and maintenance. Keep the purchase documents and invoices together for future reference.
Tell us your budget, preferred location and how you plan to use the property. We can help build a shortlist and arrange a useful viewing trip. You can also begin with our Search Complete MLS Inventory ↗ or development guide.
Share your budget, preferred location and timing. We’ll help you turn those ideas into a focused property search.
Reviewed September 22, 2026. This guide provides general buying information. Your notario, independent legal advisor and tax advisor should confirm the requirements, costs and ownership structure for your circumstances. Official sources are linked alongside the relevant topics; some are in Spanish.
Compare the same location through the practical questions that matter for a house, condo or building lot. Our specialist guides cover everyday services, water, views and the setting around each property.
Each guide opens in a new tab, keeping this page open.